

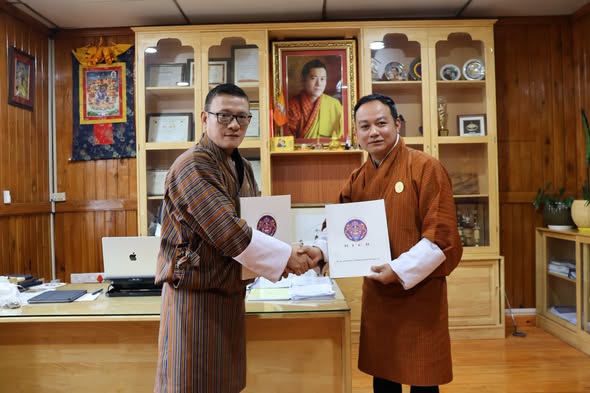
The Royal Insurance Corporation of Bhutan Limited (RICBL) and RENEW Microfinance Private Limited (RMF) signed a Credit Life Insurance Agreement, introducing an additional layer of financial protection for microfinance borrowers and their families.
The agreement, which came into effect from October 20 this year, is intended to address the financial risks that arise when a borrower dies before repaying an outstanding loan. Under the arrangement, insurance will cover the outstanding loan in such unforeseen circumstances, helping prevent the debt from becoming a financial burden on the borrower’s family or guarantors.
According to the FIs, the partnership is particularly relevant to rural and low-income households, which often depend on small loans to establish businesses, purchase agricultural inputs, acquire equipment or support other income-generating activities. For these borrowers, the death of a family member who is responsible for loan repayments can disrupt household income and leave dependants struggling to meet financial obligations.
By linking microfinance lending with credit life insurance, the two institutions aim to strengthen borrower protection and promote more responsible lending practices.
When a borrower dies unexpectedly, the consequences can extend beyond the immediate loss of household income. Outstanding loan repayments may place additional pressure on surviving family members, while guarantors who agreed to support the loan may face potential financial liabilities.
The credit life insurance arrangement is designed to address this risk by settling the outstanding loan through insurance, subject to the terms and conditions of the policy. This can help protect the borrower’s family from inheriting an unpaid debt and reduce the risk of guarantors being required to meet repayment obligations arising from the borrower’s death.
For RMF, the agreement represents an effort to extend financial protection beyond the provision of credit itself. The institution serves rural and low-income communities, particularly women, for whom access to appropriately sized loans can be important in supporting livelihoods and strengthening household financial security.
Microfinance can help borrowers establish or expand small businesses, invest in farming and livestock, and meet working-capital requirements. However, borrowing also exposes households to repayment risks when income is disrupted by unexpected events. Insurance-linked lending can help address some of these risks and make borrowing more secure.
The agreement also reflects the role that partnerships between financial institutions and insurers can play in broadening access to financial protection. While microfinance institutions provide loans to underserved communities, insurance can help manage specific risks that borrowers may be unable to absorb independently.
For households with limited savings or few alternative sources of income, an unpaid loan following the death of a borrower can create prolonged financial hardship. Settling the outstanding balance through insurance could therefore help surviving family members maintain greater financial stability during a difficult period.
The agreement is expected to provide borrowers and their families with greater peace of mind by reducing uncertainty over how outstanding loans will be handled in the event of the borrower’s death. However, the actual protection available to borrowers will depend on the policy’s coverage, eligibility requirements, exclusions and claims procedures.
The partnership comes amid wider efforts to strengthen financial inclusion in Bhutan, particularly among rural households and small entrepreneurs who may have limited access to conventional banking services. Access to credit remains important for people seeking to develop livelihoods, but the long-term benefits of borrowing also depend on whether financial products adequately account for risks faced by borrowers.
For microfinance clients, responsible lending involves more than providing funds. It also requires ensuring that loan sizes are appropriate to borrowers’ needs and repayment capacity, that terms are clearly explained and that foreseeable risks are managed wherever possible.
Credit life insurance can contribute to this approach by providing a mechanism to settle covered outstanding debt when a borrower dies. It does not eliminate every financial risk faced by a household, but it can prevent one particular event from leaving dependants and guarantors with an unpaid loan.
The agreement establishes a formal basis for cooperation in delivering this protection to eligible borrowers for both the institutions. As Bhutan continues to expand access to financial services, initiatives that combine credit with appropriate risk protection could help ensure that microfinance supports livelihoods without exposing vulnerable households to avoidable financial hardship.
The October 20 agreement marks a step in that direction, bringing insurance protection into RMF’s lending framework and reinforcing the importance of placing borrowers’ long-term financial wellbeing at the centre of inclusive finance.
Tashi Namgyal, Thimphu